The $36k Number Everyone Gets Wrong
By Vic Malone, CAPT, USN (ret) · Peak Seven Mortgage · 11/14/2026
"THIS VETERANS BASIC ENTITLEMENT IS $36,000"
You read that under your COE and wonder, what good is this VA home loan entitlement? Either it's just enough to buy a dilapidated fixer upper in EBE or if is says zero, that you can't buy at all!
So let me give
Here’s my “Ustafish”* story. Back when I first entered the Navy, there was only basic entitlement, and it was $27,500. It increased to $36,000 in 1987 and could only be used for one home purchase, so that is where the urban legend about not having more than one VA loan at a time came from. That "Usta" be true.
All that changed in 2001 and 2004 legislation creating the current system that added a second tier of entitlement on top of the existing basic entitlement. But here’s the kicker. The IT systems were never updated because the additional entitlement changed every year AND it varied by area based on the county conforming loan limit. So the COE that the VA issues uses the old IT systems and doesn’t even address supplemental entitlement other than putting in a note on the COE.
So how do you read the COE? This post walks through a real Certificate of Eligibility the way I read it, line by line, so you can do the same in about a minute.
The visible $36,000 line
The $36,000 on your Certificate of Eligibility is your basic entitlement that will guarantee a loan up to $144,000. It is 25% of the loan amount, although it can be a higher percentage for lower loan amounts.
The hidden variable second tier that is inferred
Congress added a second tier of entitlement, called bonus entitlement, tied to the county loan limit. In El Paso County that limit is $832,750 for 2026, so the total guaranty available with full entitlement is 25 percent of that, or $208,188. And since 2020, a veteran with full entitlement has no VA loan limit at all. The only limit is what you qualify for and what a lender and appraisal will support.
Let’s look at some examples:
Example 1: Never used, full entitlement
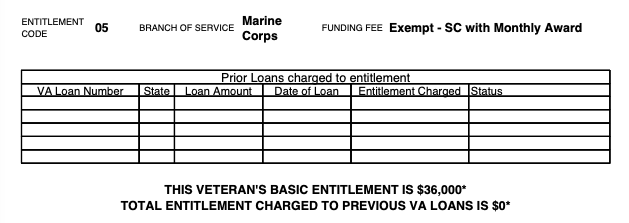

Certificate of Eligibility, Marine Corps veteran. No prior VA loans.
Marine Corps veteran. No prior VA loans. Basic entitlement: the full $36,000. Total charged: $0.
This is the cleanest case. Full entitlement means no loan limit and no down payment at any price they qualify for, and they are exempt from the funding fee as well. If the VA had a modern IT system, it would read like this:
THIS VETERANS BASIC ENTITLEMENT IS $36,000
THIS VETERANs SUPPLEMENTAL ENTITLEMENT IS $172,188
TOTAL ENTITLEMENT CHARGED TO PREVIOUS LOANS IS $0
But alas, Vic is not in charge of the VA.
Example 2: Foreclosure, and entitlement left over
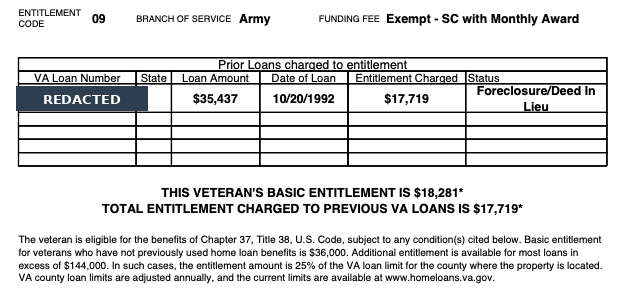

Certificate of Eligibility, Army veteran. Loan number redacted.
Army veteran. One prior VA loan, $35,437, dated October 20, 1992. Entitlement charged: $17,719 (50%). Status: foreclosure/deed in lieu. Basic entitlement left: $18,281.
Read that again. A foreclosure more than thirty years ago, and this veteran still has $18,281 of basic entitlement on the books. The foreclosure did not zero him out. Run the rest of the math for El Paso County and his remaining guaranty supports a purchase up to $761,874 with no down payment. He is also exempt from the funding fee, because he receives service-connected disability compensation.
Run your own numbers. If a prior VA loan is still using part of your entitlement, my calculator does this same math in seconds, we just need that entitlement charged.
VA Second Tier Entitlement Calculator
Example 3: Active VA loan, $0 basic entitlement left

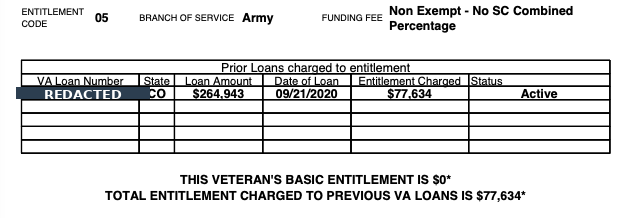
Certificate of Eligibility, Army veteran, Colorado. Loan number redacted.
Army veteran. One prior VA loan in Colorado, $264,943, dated September 21, 2020. Entitlement charged: $77,634. Status: active. Basic entitlement left: $0.
Zero sounds final. It is not. The $0 is only the basic tier. The bonus tier still applies, and the math works the same way: $208,188 minus $77,634 leaves $130,554 of guaranty, which supports a purchase up to $522,214 with no down payment, even while the first VA loan is still outstanding. This is the Tier 2 scenario I see most often, usually a veteran keeping the first home as a rental and buying the next one. One difference from the first example: this veteran is not exempt from the funding fee, so a second use at zero down carries the 3.30 percent subsequent-use fee.
Run your own numbers. Enter the entitlement charged on your COE and see what a second VA loan supports.
VA Second Tier Entitlement Calculator
The funding fee line
The COE also shows whether a veteran is exempt from the VA funding fee. Two of the three veterans above are exempt because they receive service-connected disability compensation. The third is not, so the subsequent-use fee applies on the next loan. Check that the line matches what you expect, and tell your lender.
You do not need the COE before you call me
This is the part veterans put off, and there is no reason to. You do not need to go get your Certificate of Eligibility before we talk. I pull it in a matter of minutes while we are on the phone, and it tells us both exactly where you stand.
What to do today
Find basic entitlement on your COE.
Find entitlement charged to prior loans and note whether it is zero.
If it is not zero, read the prior-loan table and see which loan is using entitlement and whether it is still open.
Check the funding fee line.
Run the numbers on the entitlement calculator, or call me and I will run them with you.
Do that before you write an offer.
Where I come in
A COE is one document, and every veteran’s file has its own details.*
* For those that stayed with me, “Ustafish” is a submarine term from an old sea story from the sub you “Usta to” be attached to. “On USS Flying Fish we used to do it this way”, ie Ustafish story. But enough, if you want to know what your entitlement supports, call me or start an application.
Bring your questions. Leave the COE to me.
719-304-4900
Vic Malone
CAPT, USN (ret)
Broker Owner
Peak Seven Mortgage LLC, NMLS #1084279. Company NMLS #1712479. Vic Malone, NMLS #1084279. 102 S. Tejon Street, Suite 1100, Colorado Springs, CO 80903. Equal Housing Opportunity.
